


VA Home Loans in Oklahoma
If you are a Veteran, active-duty service member, member of the National Guard or Reserve, or an eligible surviving spouse, a VA home loan may be one of the most valuable home financing benefits available to you.
VA-backed home loans are made by private lenders and guaranteed in part by the U.S. Department of Veterans Affairs. For eligible borrowers, the program can offer significant advantages, including the possibility of buying a home with no down payment and no monthly private mortgage insurance (PMI). Veterans Affairs
At Lincoln Lending, we help Oklahoma homebuyers understand how their VA benefit works, determine whether they may be eligible, and walk through the mortgage process from pre-approval through closing.
What’s a VA Home Loan?

A VA home loan is a mortgage program designed to help eligible Veterans, service members, and certain surviving spouses purchase, build, improve, or refinance a home.
The loan itself is generally made by a private mortgage lender. The VA guarantees part of the loan, which can allow lenders to offer favorable terms to eligible borrowers. Veterans Affairs
For a home purchase, the VA loan is generally intended for a property you will occupy as your primary residence.
Benefits of a VA Home Loan
Depending on your eligibility and financial situation, VA financing may offer several important benefits:
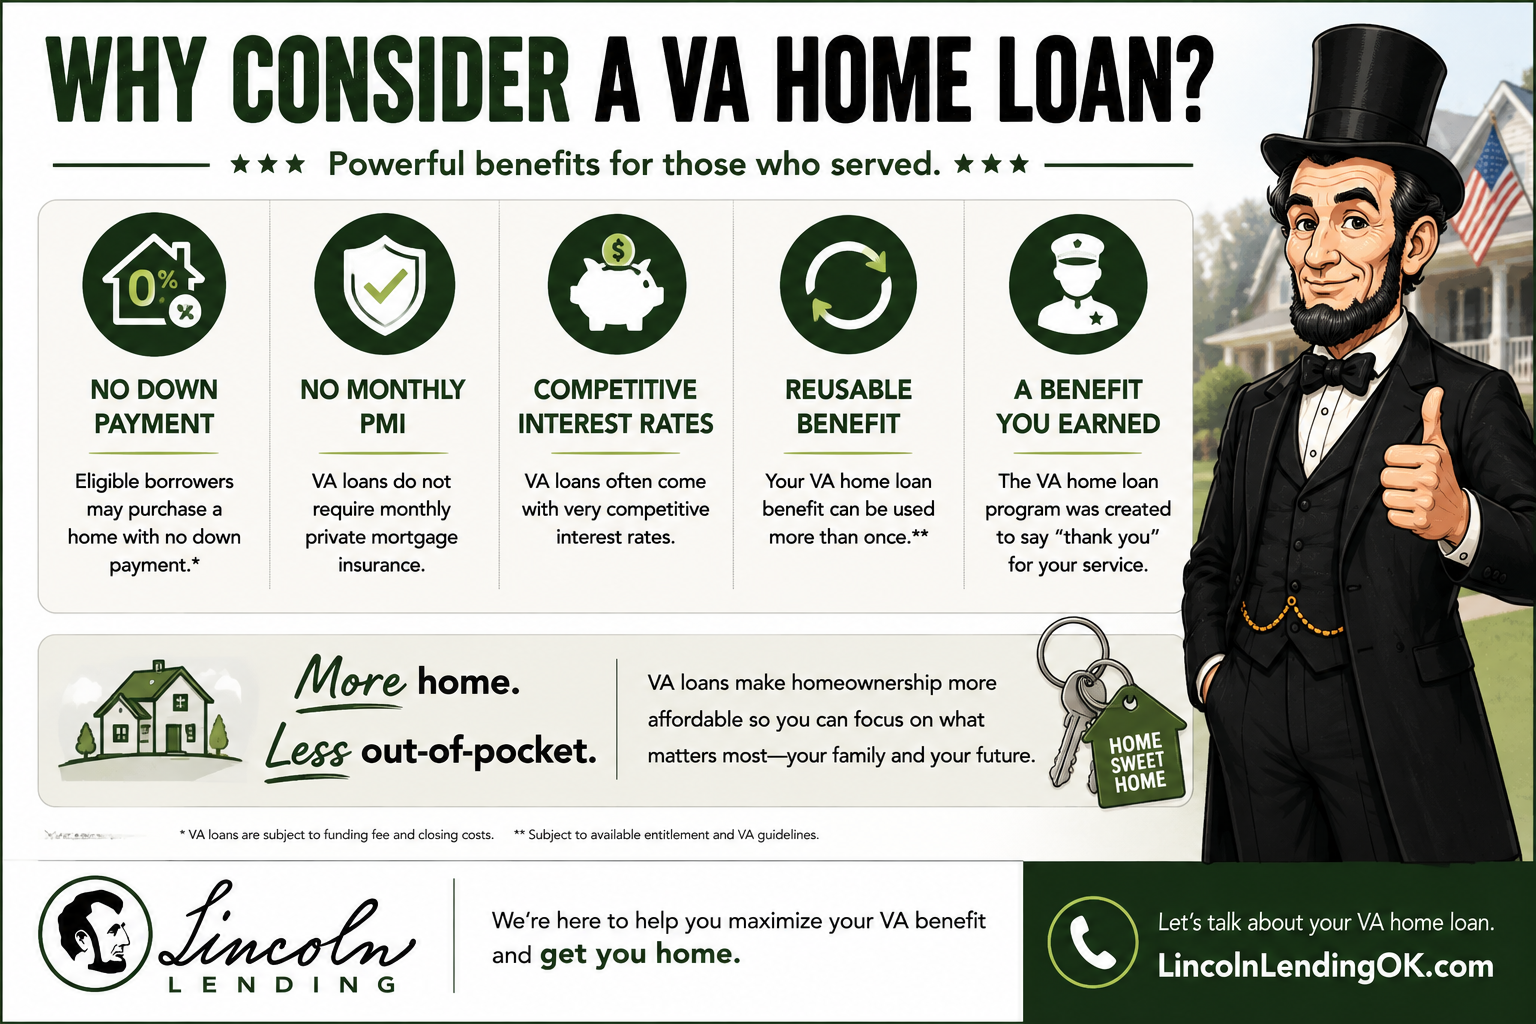
No Down Payment May Be Required
Many eligible VA borrowers are able to purchase a home without making a traditional down payment. VA notes that nearly 90% of VA-backed loans are made with no down payment. Veterans Affairs
That does not necessarily mean you will need zero dollars at closing. Closing costs, prepaid expenses, inspections, deposits, and other transaction costs may still apply.
No Monthly Private Mortgage Insurance
VA-backed loans do not require monthly private mortgage insurance. That can make a meaningful difference in the monthly payment compared with some other low-down-payment mortgage options. Veterans Affairs
Potentially Competitive Loan Terms
Because the VA guarantees a portion of the loan, lenders may be able to offer favorable financing terms. Interest rates and lender fees can still vary, so the actual terms depend on the lender and the borrower’s circumstances. Veterans Affairs
The Benefit May Be Used More Than Once
A VA home loan benefit is not necessarily a one-time benefit. Depending on your entitlement and circumstances, you may be able to use it again after previously having a VA loan.
Who Qualifies for a VA Home Loan?
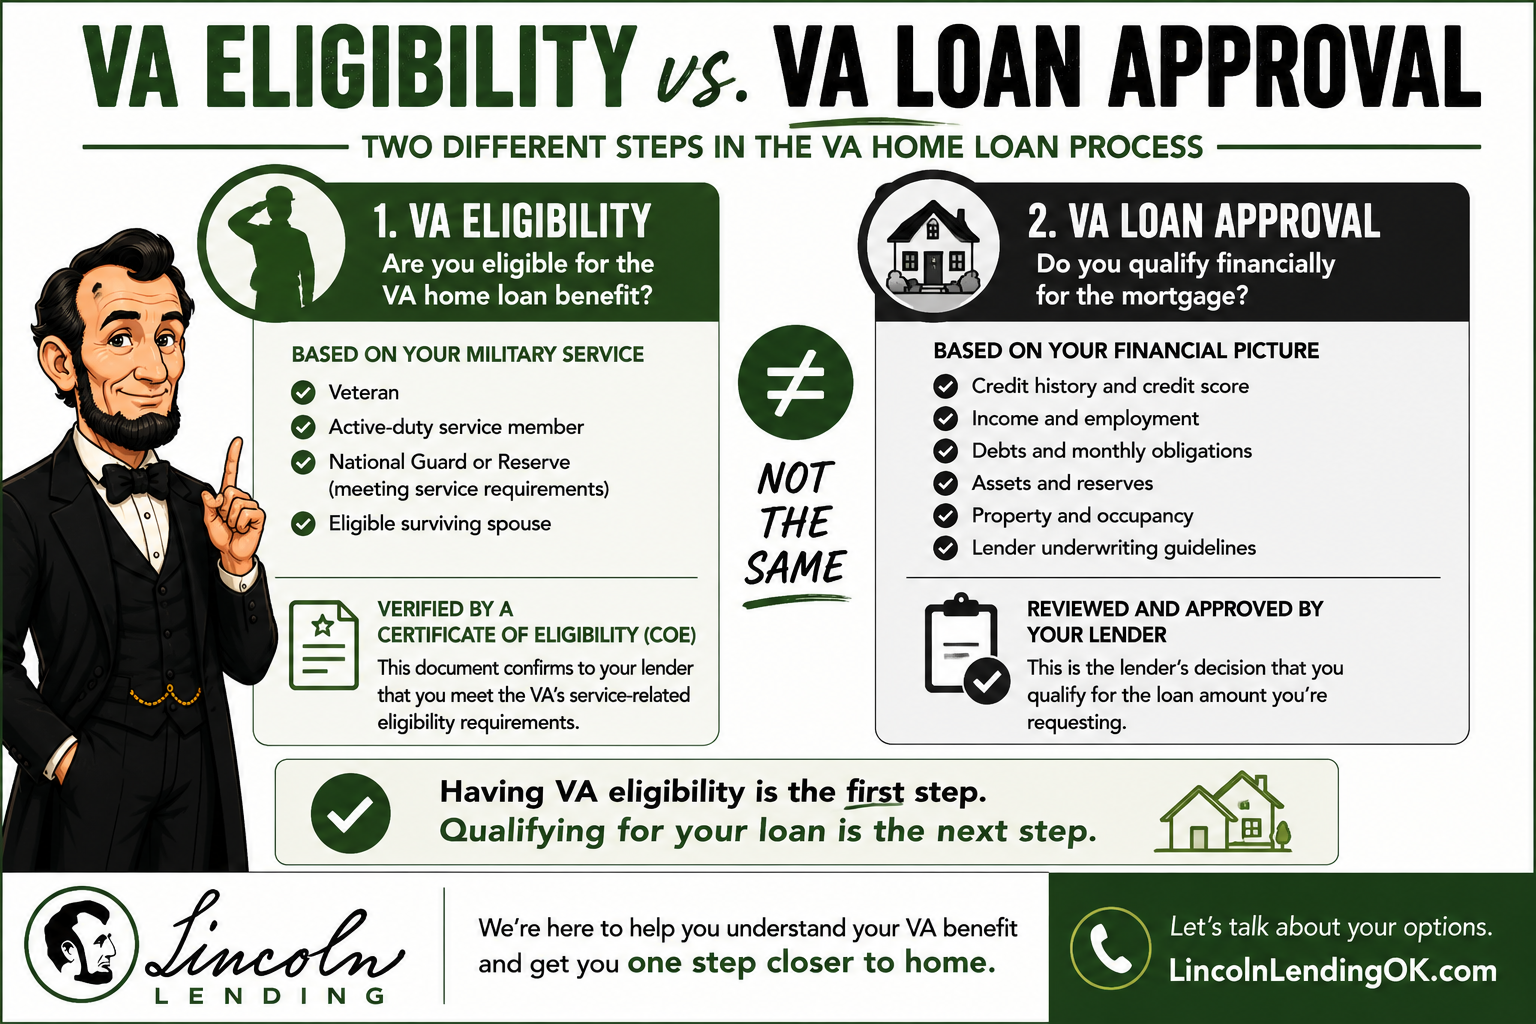
VA home loan eligibility is based primarily on your military service history and duty status.
Potentially eligible borrowers may include:
Veterans
Active-duty service members
Certain National Guard and Reserve members
Certain eligible surviving spouses
The specific service requirements vary depending on when and how you served, so there is not one simple number of service days that applies to everyone.
The best way to confirm eligibility is through a Certificate of Eligibility, commonly called a COE.
What Is a VA Certificate of Eligibility?
A Certificate of Eligibility is the document that verifies to a lender that you meet the VA’s service-related eligibility requirements for the VA home loan benefit. You can request one here: Veterans Affairs
A COE is important, but it is not the same thing as a mortgage approval. Think of it this way: The COE helps establish that you are eligible to use the VA home loan benefit. The lender still has to determine whether you qualify financially for the mortgage you want.
Your lender will still review your income, credit history, debts, assets, and the property involved in the transaction. Many borrowers do not need to obtain the COE before contacting a lender. A lender can often help request it electronically.
Is There a Minimum Credit Score for a VA Loan?
The Department of Veterans Affairs does not establish a universal minimum credit score for VA home loans.
Individual lenders may have their own minimum credit-score requirements or underwriting standards. That is why it is not a good idea to assume you cannot qualify simply because of a score you saw on a credit-monitoring app.
A lender will look at the overall financial picture, including:
Credit history
Income
Monthly debts
Assets
Proposed housing payment
If your credit is not where you would like it to be, the right first step is often to have a mortgage professional review the situation before making major changes on your own.
What About Debt-to-Income Ratio?
Your lender will review your monthly obligations in relation to your income when determining how much mortgage debt you may reasonably be able to carry. VA underwriting also considers the borrower’s overall ability to repay the loan rather than relying on one number alone. This is another reason why trying to determine qualification from a single online calculator can be misleading.
Do VA Loans Require a Down Payment?
Eligible borrowers may be able to purchase with no down payment.
Even though VA does not require it, a down payment may still make sense in some situations, depending on the purchase price, entitlement, funding fee, appraisal, or a borrower’s goals. The lender can help you compare the options.
What Is the VA Funding Fee?
Many VA borrowers pay a one-time VA funding fee.
The fee helps support the VA home loan program and is one reason the program can offer benefits such as no required monthly mortgage insurance. Veterans Affairs
The amount of the funding fee can depend on factors such as:
The type of VA loan
Whether this is your first or subsequent use of the benefit
The amount of your down payment
Some borrowers are exempt from the VA funding fee, including certain Veterans receiving or entitled to receive VA disability compensation and certain other eligible borrowers. More info avaiable at Veterans Affairs
For many borrowers, the funding fee can be financed into the loan rather than paid entirely in cash at closing. Veterans Affairs
Does the Home Have to Be My Primary Residence?
Generally, yes.
A VA-backed purchase loan is intended for a home you plan to occupy as your residence. VA financing is not generally intended as a standard loan program for purchasing vacation homes or traditional investment properties. The property will also typically need a VA appraisal.
Is a VA Appraisal the Same as a Home Inspection?
No.
A VA appraisal helps establish the property’s value and evaluate certain VA property requirements.
A home inspection is different. An inspection is intended to help you understand the condition of the property, including items such as the roof, electrical system, plumbing, HVAC, structure, and other components.
VA specifically notes that an appraisal is not the same thing as a home inspection.
We generally recommend that buyers understand the difference and consider an independent home inspection.
Can I Use a VA Loan More Than Once?
Yes, in many situations.
If you have used your VA benefit before, you may still have entitlement available, or you may be able to restore entitlement depending on your circumstances.
This can become more complicated if you currently have another VA loan or have previously used part of your entitlement.
Rather than assuming you have “used up” your VA benefit, have a lender review your Certificate of Eligibility.
What If I Was Previously Turned Down for a VA Loan?
A previous denial does not necessarily mean you will never qualify.
Your circumstances may have changed.
Your income may be higher. Your debts may be lower. Your credit profile may have improved. You may also be working with a different lender that evaluates the file differently.
If you are eligible for the VA benefit but do not currently qualify for the mortgage you want, the better question is often: What would I need to change to put myself in a stronger position?
That gives you a plan instead of simply assuming the answer is no.
How Do I Get Pre-Approved for a VA Loan?
The VA homebuying process generally involves confirming eligibility, reviewing your finances, choosing a lender, finding a property, obtaining a VA appraisal, completing underwriting, and closing on the home. Veterans Affairs
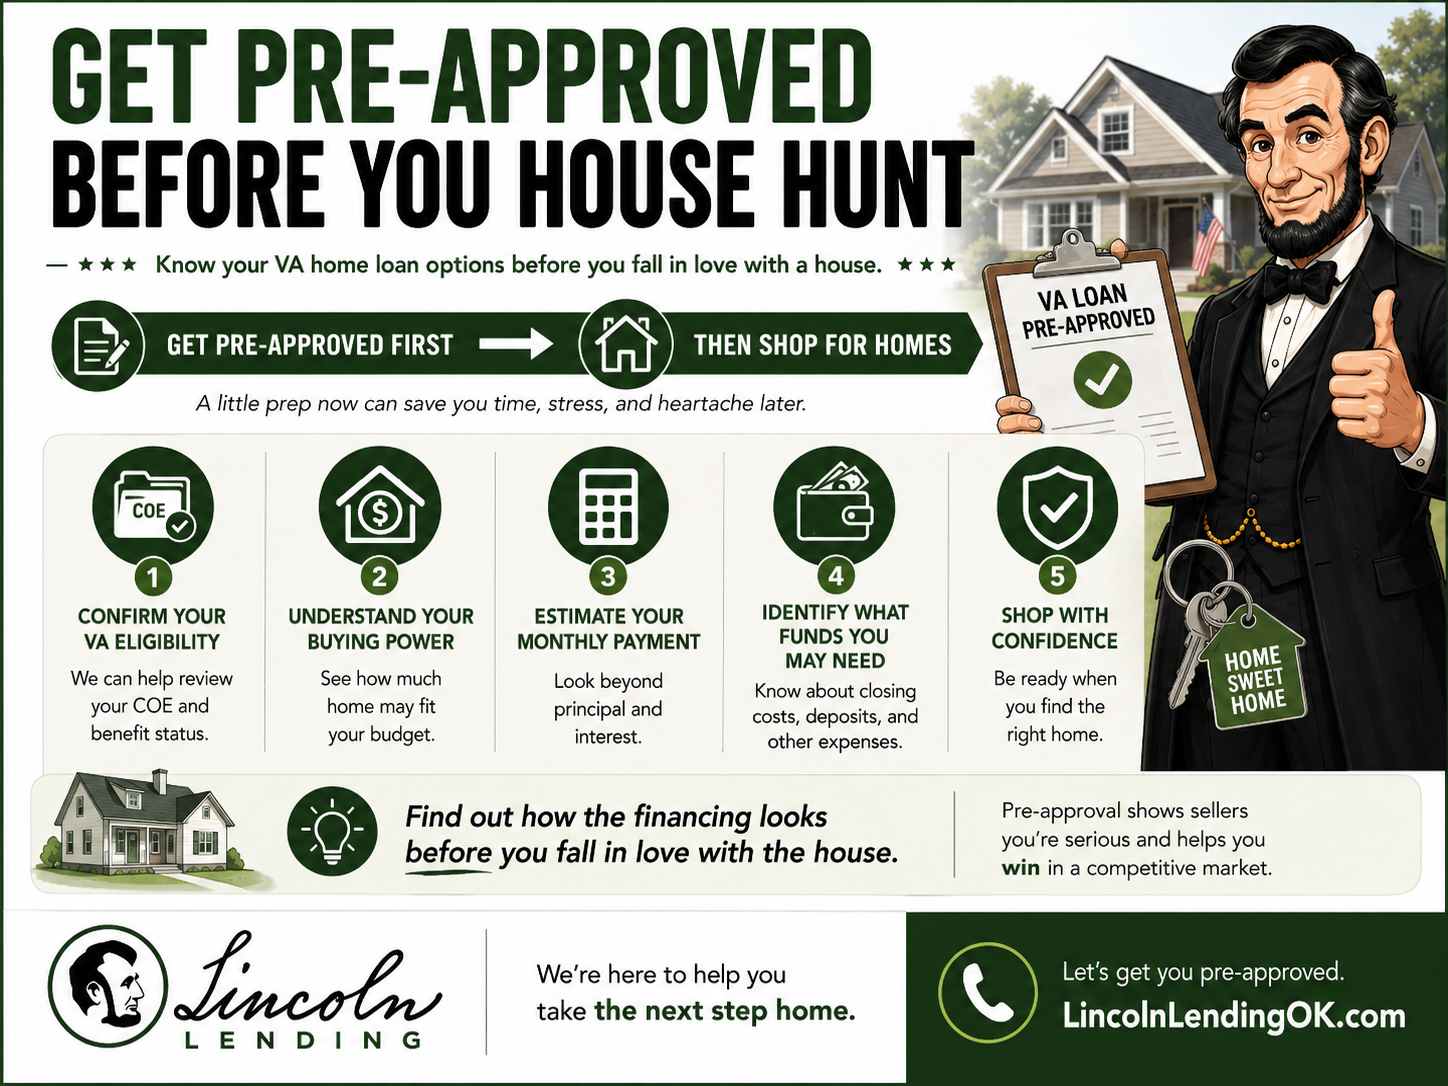
At Lincoln Lending, we recommend starting with pre-approval before seriously shopping for a home.
A pre-approval can help you understand:
Whether your VA eligibility can be established
How your credit looks from a mortgage standpoint
Approximately how much you may qualify to borrow
Your estimated monthly payment
How much cash you may need at closing
Whether a funding fee may apply
What price range may be realistic
That information can help you and your Realtor focus on homes that make sense for your budget.
Why Work With Lincoln Lending for a VA Loan?
VA loans have their own rules, terminology, and underwriting considerations.
Our goal is to help make the process understandable.
Lincoln Lending is based in Norman, Oklahoma, and works with homebuyers throughout Oklahoma. We believe borrowers deserve clear answers, realistic payment estimates, and personal service rather than feeling like another number in a large call center.
Whether you are ready to buy now or are just trying to understand your VA benefit, we can help you determine the next step.
Ready to Explore Your VA Home Loan Benefit?
If you think you may qualify for a VA home loan, start by talking with Lincoln Lending.
We can help review your eligibility, request your Certificate of Eligibility when appropriate, look at your financial situation, and explain your financing options.
Get pre-approved before you start house hunting so you know what the financing looks like before you fall in love with a home.
How It Works
Own your dream home in three simple steps:
Step 1
Schedule Home Loan Coaching Session
Step 2
Get pre-approved for your mortgage
Step 3
Move into your dream home!
Wondering what happens during a Home Loan Coaching Session?
Visit our Coaching page to see a real Coaching Session.
Articles
Have a question about your VA Loan benefit? Check out our most popular articles about VA Loans:


